SAF-T in Bulgaria: What Finance Leaders Need to Do Now
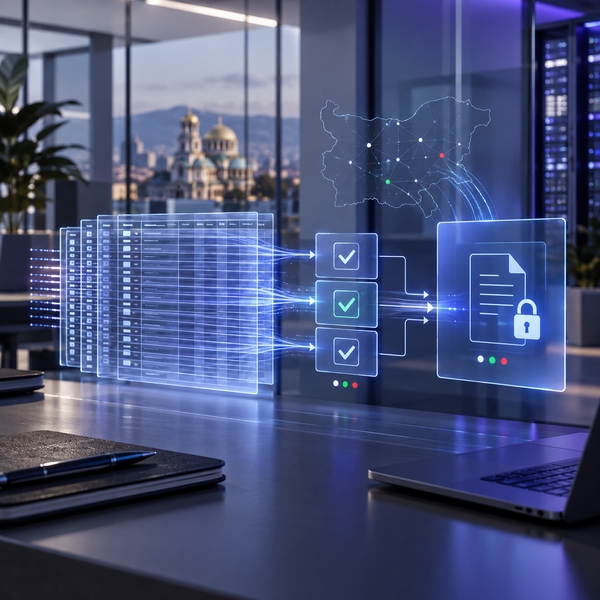
The difficult part of SAF-T is not producing XML. It is proving that the records inside it are complete, traceable, correctly interpreted, and repeatable under a filing deadline
Treat SAF-T as a data and control program
The Standard Audit File for Tax gives tax authorities structured accounting and transaction data in a machine-readable form. That changes the nature of compliance. Instead of preparing a limited set of reports after period end, an organization may need to explain the completeness, consistency, and lineage of detailed records generated throughout the year.
For Bulgarian businesses, the weak response is to frame SAF-T as an export project owned by IT. A technically valid XML file can still contain incomplete master data, inconsistent tax treatments, unreconciled balances, or transactions that cannot be traced to their source. The stronger response starts with finance and tax ownership, then uses technology to produce repeatable evidence.
The National Revenue Agency publishes the applicable schema, submission information, and implementation materials. Those official materials should be treated as the baseline. Interpretation of scope and tax treatment should be confirmed with qualified Bulgarian advisers; software design must follow the validated obligation, not substitute for it.
Map the obligation to real business processes
Begin with the legal entities and periods in scope, then map the transactions that create reportable data. Sales, purchasing, general ledger, payments, inventory, fixed assets, and master data often cross system boundaries. The relevant question is not only where a journal entry sits, but how its source, counterparty, document, tax treatment, and settlement can be reconstructed.
This exercise frequently exposes data that is added late in spreadsheets or held by another function. Product codes may be maintained by operations, counterparty identifiers by sales, payment references by treasury, and fixed-asset information by local finance. SAF-T makes those ownership gaps visible because a structured file cannot rely on tacit knowledge.
Document every source field, transformation, validation, and reconciliation. Where data is derived, record the rule. Where it is unavailable, decide whether the source process must change, an integration is required, or a controlled enrichment step is justified. Temporary manual work should have an owner and retirement plan.
Build reconciliations before building the file
File generation should begin only after the organization defines how it will prove completeness and accuracy. Control totals should reconcile the SAF-T output to the general ledger and relevant subledgers. Opening balances, period movements, tax amounts, customer and supplier activity, inventory, and fixed assets need explicit reconciliation rules.
Technical validation checks whether the output conforms to the schema. Business validation asks whether the data makes sense. Both matter. Duplicate identifiers, missing document references, unexpected tax codes, invalid dates, inconsistent signs, or unexplained differences can survive a purely technical check.
Design an exception process with thresholds, ownership, evidence, and approval. The target is not a file that passes once. It is a controlled monthly or annual operating process that produces the same result under deadline pressure and survives staff changes, upgrades, and regulatory updates.
Test scenarios, volume, and corrections
A representative test pack should include normal transactions and the cases most likely to break mappings: advances, credit notes, reversals, foreign currency, corrections, late documents, self-assessed tax, intra-EU activity, imports, manual journals, opening balances, settlements, and historical migrations. The exact set depends on the Bulgarian entity’s business model.
Volume testing matters because a mapping that works on a sample may fail when millions of records are extracted, transformed, validated, and uploaded within an operational window. Teams should test processing time, memory, retry behaviour, file segmentation where relevant, access permissions, audit logs, and secure retention.
Run at least one end-to-end rehearsal using a closed period. Finance should reconcile the result; tax should assess the treatments; IT should verify repeatability and security; and an accountable business owner should approve readiness. Defects should be classified as source-data, configuration, mapping, process, or interpretation issues so the correct owner fixes the cause.
Create durable ownership
A sustainable SAF-T model separates accountability clearly. Finance owns accounting completeness and reconciliation. Tax owns interpretation and tax treatment. Data owners maintain master data. IT and implementation specialists operate the extraction and technical controls. Compliance leadership decides whether exceptions are acceptable and documented.
Regulatory schemas, tax rules, ERP releases, integrations, and business processes will change. Include SAF-T in release management and change impact assessment. A new tax code, acquisition, warehouse system, payment provider, or chart-of-accounts change can affect the output even when the SAF-T solution itself has not changed.
The leadership test is simple: can the organization explain where every material field came from, why it was treated that way, who reviewed it, and how the submitted file reconciles to the books? If not, the remaining work is not cosmetic. It is the core of compliance readiness.
A 90-day readiness sequence
In the first month, confirm scope, ownership, source systems, and the official schema; profile required data before discussing cosmetic reporting. In the second, build mappings, reconciliation rules, and a representative scenario pack. In the third, run an end-to-end rehearsal, resolve root causes, document the operating procedure, and obtain accountable approval.
The sequence is deliberately evidence-led. It prevents teams from spending weeks polishing an export while fundamental questions about completeness, interpretation, or ownership remain unanswered.
Minimum evidence before the first live filing
The team should be able to produce and explain each item without relying on one individual’s memory.
- A confirmed register of entities, periods, source systems, and transactions in scope.
- Field-level mapping from source data to the current NRA SAF-T schema.
- Documented reconciliations to the general ledger and relevant subledgers.
- A tested exception, correction, approval, and resubmission process.
- Named finance, tax, data, technology, and compliance owners.
- Evidence from at least one full-volume end-to-end rehearsal.
Need Help?
D6 Global SAF-T compliance solution was built to minimize disruptions for you and your team.